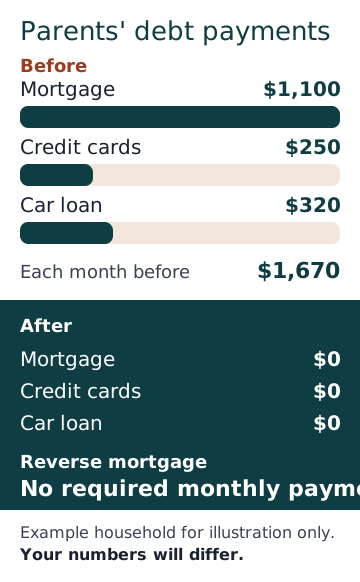
Quick answer: It can make sense when parents 55 or older want to stay in their BC home but debt payments are squeezing their income. A reverse mortgage pays off those debts with no monthly payments. Interest accrues over time and reduces home equity, and they keep paying property taxes, insurance and maintenance. Decide together, with independent legal advice.
Whether your family is in Vancouver, Victoria, Kelowna, Surrey or another BC community, sit down with the people you trust. These questions help you have an open, useful conversation before deciding.
Should my parents get a reverse mortgage? Start with the reason for the conversation
What problem are we trying to solve?
Is it the mortgage payment, several debts at once, or not enough left each month for everyday costs? Be specific. Look at the whole retirement budget, not just the debts.
Which debts would be paid off, and what would the monthly budget look like afterward?
Write down each debt, its balance and payment. Then make a simple budget showing which payments would end and which costs would stay.
How much money is actually needed?
Ask whether the amount is limited to what the debt plan needs, and how the money would be paid out. Get the details in writing.
If this is part of a bigger money talk, our guide to talking to aging parents about money has scripts and a checklist.
Compare the other options fairly
What alternatives have we considered?
Ask whether a refinance, a HELOC, another loan or a debt repayment plan could work. Each has different costs and payments, and qualifying depends on income. Downsizing may also be worth discussing. If that is a sore spot, read what to do when parents won't downsize.
Could we manage the payments on a cheaper option?
A loan with a lower overall cost is a poor fit if its monthly payments are too hard to carry. Compare both: the cost over time and the effect on the monthly budget.
Understand how a reverse mortgage affects the home
How does interest build?
With a reverse mortgage, interest is added to the amount owed. Interest accrues over time and reduces your home equity. Ask for written examples showing how the balance and remaining equity may change.
What fees should we expect?
Ask for a written list of costs, such as legal, appraisal and setup fees, and what applies if the loan is repaid early.
What happens if we sell, move or need long-term care?
Ask when the loan must be repaid and what happens if plans change, including if one borrower moves into care while the other stays home. Read the contract with an independent lawyer before signing.
Talk about the household costs that remain
No regular monthly mortgage payments are required. You still keep up property taxes, home insurance and upkeep.
Plan for utilities and repairs too, and decide who in the family can help keep track of due dates if your parents want that help.
Reverse mortgage for elderly parents: the family and estate conversation
A reverse mortgage for elderly parents is a family decision. This is the place to talk it through together.
How much equity might remain for the estate?
What is left depends on how long the loan is in place, the costs, and the home's value at the time. If leaving an inheritance matters, say so. If your parents would rather help family now, see living inheritance in Canada.
What would the family need to do when repayment is due?
Ask how long the estate would have to repay the loan, and whether family members could repay it and keep the home.
Can everyone speak openly without pressure?
The homeowner should be able to ask questions, take time and speak privately with an independent professional. Adult children can share concerns and help review information, but the homeowner's wishes guide the decision.
A simple way to end the conversation
Before anyone signs, the homeowner should be able to answer these in their own words:
- Which debts would the reverse mortgage pay off?
- What bills would remain?
- How does interest affect the balance and home equity?
- When might the loan have to be repaid?
- What alternatives were considered?
- Who reviewed the documents independently?
For a full checklist, see the questions to ask before getting a reverse mortgage in our free BC guide.
City guides: Help for parents in Surrey, Help for parents in Richmond, Help for parents in Kamloops.
Take the 60-second Living Inheritance Quiz
Matt Blake, Mortgage Broker (BCFSA Licence MB600487).
BRX Mortgage Inc. (BCFSA Licence X301291).